Most OTAs will die. The spread they lived on moves one layer down.
TL;DR [show]
A company-level forecast for online travel agencies: converging agent and supplier capabilities favor consolidation and closure, leaving fewer independent firms. The essay follows the trip, the distribution spread and the obligations behind booking, distinguishing proven integrations from predictions. Profitable specialist transformation remains a real survival outcome, exposed to further bypass as agents improve.
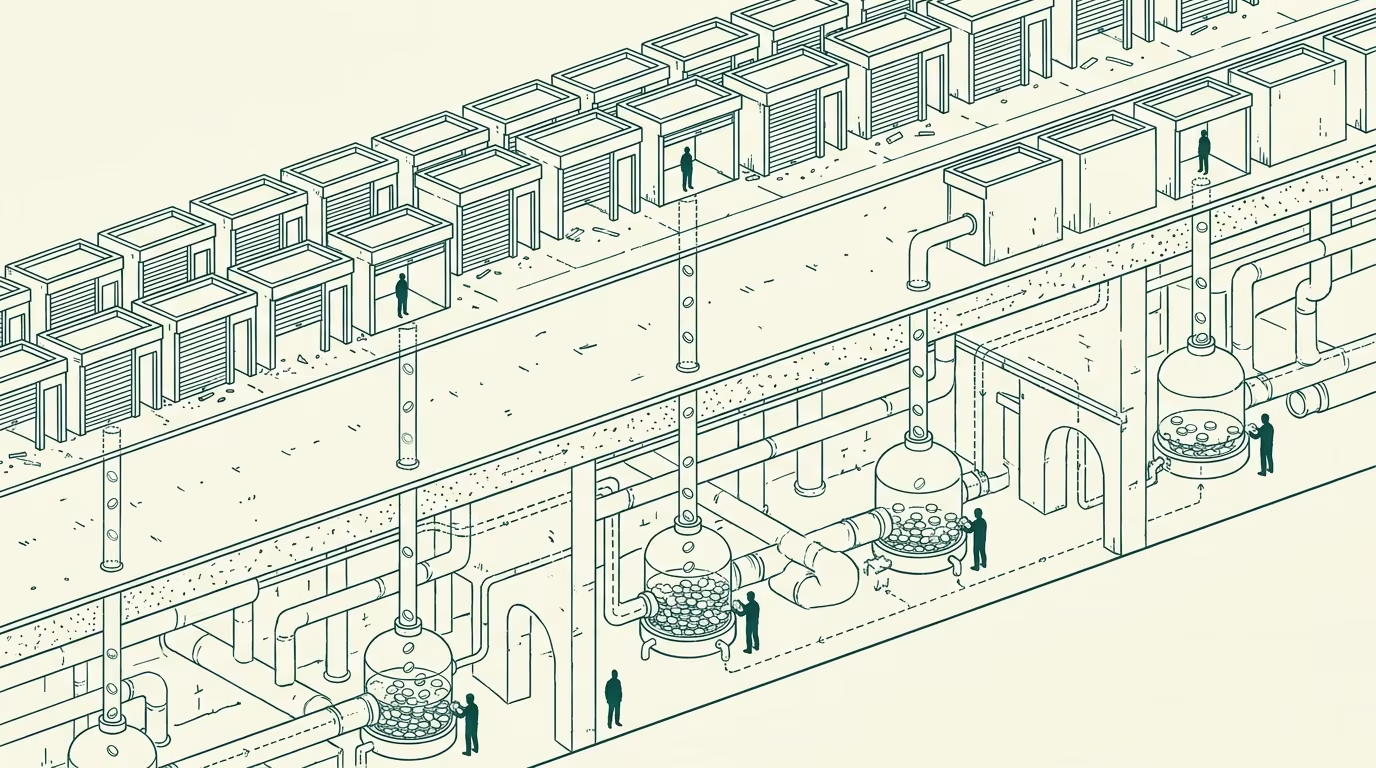
Having recently prepared a larger industry report for one of the large consultancies on the state of the travel industry, I wanted to impart a prediction to the rest of you.
OTAs will (largely) die.
Every age claims a first casualty. The agentic age will claim the travel agency.
Start with the companies. The independent field shrinks by acquisition, merger and closure, because the capabilities that once justified a separate company are converging inside the agents and inside the suppliers those agents call. Some very good businesses will be bought, some will survive only by becoming very different businesses, and others will run out of reasons to exist before they run out of bookings.
By 2030–2035, I expect more than nine in ten of today's independent consumer OTAs to have been acquired, merged or closed; the few that stay independent by reinventing themselves count as survivors. More than half the volume those companies handle today will have migrated to suppliers, to GDSs or to a new generation of agent-facing infrastructure, and the margin on much of what remains compresses too. Company count, booking volume and margin are different losses, and I expect all three.
Much of the function goes too, only slower, because the agentic era compresses intermediation. A traveller who wants a direct economy flight between YYZ and LGA will not need ten intermediaries between their agent and the airline, or five, or even two. The most basic path needs none: the traveller's agent calls the airline's own API (NDC, in the trade's shorthand) and books. Complex chains do not compress overnight (multi-carrier itineraries, groups, disruption, the trips where somebody has to carry the risk), and that is where the booking functions last longer than the companies. Somebody still has to find the fare, join the itinerary, carry the risk and process the refund on those, and there will be money in all of that, and more money in influencing which offer the traveller gets shown.
So the function shrinks to where the complexity and the risk actually live. A minority of today's incumbents will earn that remainder, underneath the new interface, and they will hold it only for as long as the agent cannot reach around them. It keeps learning to.
The agent keeps the trip
An OTA was a place you went to compare. Its first job was getting you there and its second was getting you back, and for twenty years it rented the first visit from Google and tried to buy the second with price, service, points, a familiar checkout, an app, an email programme. Imperfect, expensive, and sometimes very effective.
The agent carries the reasons for returning somewhere else. It remembers your dates, your budget, which airports you tolerate, whether you check a bag, how long a connection you will put up with, and none of that is the agency's alone any more. A good previous booking becomes evidence about an agency rather than a habit of visiting its site. The platforms know what they want. Sabre's chief executive, on the company's latest earnings call, said the larger agentic players are after “an end-to-end experience for the consumer where they stay captive to that platform for the entire experience.”
AI Overviews showed what happens when the answer arrives before the visit. Booking's chief executive told analysts in August that the AI overview at Google “probably has done it” to SEO, and his company had already written down KAYAK by $457M (goodwill and intangibles) on “expected increases in customer acquisition costs” for its meta-search business. The agent carries the same logic past discovery and into the transaction. Google's August hotel-booking rollout lets US English-language users carry a booking through inside Google with participating hotel and OTA partners; the partner stays merchant of record and handles support, and flights still hand you off to an airline or a booking site to pay. The boundary has moved for one category and is still upstream for the other, and Google has said where it is going: “In the future, we'll also make it possible to finish booking flights and hotels directly in AI Mode.”
The incumbents have put the same thing in writing, to the SEC. Booking's annual report warns that “AI agents may further evolve into full-service booking platforms, increasing competitive pressure and disintermediating OTCs” (online travel companies, in its own shorthand), and that “Travel service providers may offer lower prices through direct or AI-enabled channels.” Expedia's says that “Any failure to effectively navigate this 'agentic' revolution could have a material adverse effect on our business”. Risk factors are written by lawyers to cover everything. These two cover the essay.
Duffel's Muse announcement describes a connector through which US users can search, book and manage flights, with humans behind it for support. Duffel's chief executive calls AI “one of the biggest new distribution channels in travel”. So infrastructure can complete a trip inside an agent, today, without a consumer agency's website anywhere in the flow. That proves the capability, not the market share, and the capability is the part that compounds.
Then there is the branded counterexample. Expedia's ChatGPT instructions describe installing its app, searching in the conversation and finishing checkout on Expedia; the app can also be suggested in response to a generic travel request. Expedia keeps the transaction and the trip record. An agency can still be the destination after the agent has done the choosing, provided it built for the platform early and gave the traveller a reason to install it.
The instruction changes the supplier
Five requests. I made them up; the choices they force are real.
“Find me a flight to Lisbon next Friday” leaves the agent a lot of room. Installed tools, access, coverage, speed, what worked last time. An integration that reliably returns bookable offers earns repeat calls without being the cheapest agency in every case.
“Book it on Expedia” is a different instruction. The traveller has named the agency and an assistant should respect that or explain why it cannot. A remembered preference can matter too, even when the brand is missing from the latest sentence. Brand attachment does not vanish because somebody else is typing.
“Book it on Expedia” can also get a smarter answer, from an assistant set up to disagree: “I sure can, it's $500 for a six-hour trip, but I also found a $400 offer on another site and a $520 offer for a four-hour trip on a third. Oh, and remember you're having a hip replacement two weeks before this trip, so a premium seat will be far more comfortable, and it's only $550 on a fourth.” The instruction was respected and the brand still had to win the booking, against an alternative drawn from a medical calendar no agency will ever see.
“Get me the cheapest workable weekend in Europe” moves the agency into a wider comparison that somebody else now runs. Flight price now competes with the hotel, the transfer and the traveller's time, so a cheap ticket loses to a dearer ticket that makes a cheaper trip. The old core skill, finding the lowest fare, becomes one input into somebody else's objective function.
“Take these six people to three cities, with two different returns and a wheelchair connection” rewards execution. Whoever can construct, issue and service that journey keeps a role after the agent has understood the request, because understanding an itinerary and being responsible for it are different capabilities.
The spread finds another address
Start with hotel commissions, and keep the units straight. BCG's hotel-distribution analysis puts the OTA commission at 15 to 30%. That is what a hotel pays for distribution; it is not an agency's margin and it is not a flight commission (most airlines stopped paying those a generation ago, which is why flight agencies live on fees, markups, ancillaries and incentives instead). The same article expects AI-era fees for “prominence and relevance” in recommendations. It is a forecast about distribution economics, not evidence of an existing tariff for buying an agent's answer.
The platforms draw these lines themselves. In OpenAI's published Instant Checkout policy, the fee on a completed purchase does not buy organic product ranking; checkout availability can, in OpenAI's own words, be a factor “when ranking multiple merchants that sell the same product.” Which product and which merchant are different decisions. A useful integration can win the second without anyone having bought the first, and a retail policy says nothing about the terms of every travel integration.
There are, however, several places to collect rent. A platform can sell attention. A supplier can offer terms that make its inventory more attractive. A connector can shape which offers exist to be compared at all. The traveller may understand one of those arrangements and never see the other two. Opacity survives without anybody secretly auctioning organic rank; it just moves to a layer with no page to inspect.
A supplier business can work
The strongest objection is practical. An agency already pays somebody for customers, so why should one more paid channel kill it? An agent could replace a marketing budget and an expensive consumer interface with a cheaper stream of bookings. A supplier earning less per booking could earn more in total. That is a credible business and some companies will build it.
Expedia already has. Its Q2 2026 results reported B2B gross bookings up 21% against 8% in B2C, with a B2B adjusted EBITDA margin (on revenue) of 24.8%, down 258 basis points, against 33.2% in B2C. Faster growth, thinner margin, somebody else's logo on the receipt. That is what being a utility looks like on a P&L, and Expedia has been one for years, which makes it the best placed of the three large groups (Booking, Expedia and Trip.com) to carry on being one. It proves partner distribution can grow and make real money, and that a new channel need not be worse on every line.
The pressure is on repeat allocation. The old channel let you turn a paid first booking into a customer who came back on their own (Expedia's chief executive reminded analysts in August that “two third of our bookings in our consumer brands come direct”, and that direct two thirds is the asset under contest); the agent stays in charge of choosing the supplier for the next booking, and every transaction becomes another chance to compare, switch or renegotiate. Old customers were never entirely free to keep either; ask anyone who has run a retargeting budget. The difference is that the agent compares by default, and loyalty to a supplier is something it has to be told to have.
An agent may still prefer one reliable intermediary that handles inventory, payment, ticketing, refunds and servicing over assembling five providers for every trip. The economics of integration and accountability do not disappear because the interface gets smarter, and they can make a capable intermediary more valuable. That is an argument for a few strong providers, not for preserving the present field of overlapping agencies.
The dangerous supplier is the interchangeable one, and interchangeable is the default, because most of the field sells the same thing. The published fares come out of the same GDS and NDC pipes under similar terms, the hotel rates come out of the same beds, and the differences agencies spent twenty years building sat exactly where the agent now stands: the search screen, the markup, the marketing. A shared fare does not become scarce because one agency has a nicer results page. The agency has to add access, terms, protection or execution worth choosing, and few independent firms will retain that difference once the agent can compare and coordinate the common parts itself.
Convergence makes consolidation pay
Losing traffic does not kill a company. A profitable agency with fewer direct visitors is still a company, and I have watched plenty of them run for years on a shrinking channel. The question is how many separate firms the new distribution system has an economic reason to support.
Fewer. Dozens of consumer agencies maintain overlapping coverage, overlapping airline integrations, separate payment stacks, separate fraud controls, separate service desks and separate acquisition machines. If the customer increasingly begins at a shared agent, several of those businesses are competing to supply the same request with much of the same inventory, and price comparison reaches the supplier layer as well as the consumer screen.
Travel already combines capabilities this way. Etraveli's 2019 acquisition of TripStack and Flight Network brought integration technology and an agency business into a larger group; Flight Network was the independent in that combination. Prosus's completed acquisition of Despegar put an OTA inside a broader consumer ecosystem. Strategic deals, not distress, and no agent was involved. They show how fewer independent owners can coexist with useful technology, continuing brands and sellers who were paid.
For the unsold firm, closure arrives when neither the remaining direct business nor the new channel covers the operation it still has to run. An agency's costs are not all variable. Accreditation and the bond behind it, settlement obligations to the airlines, distribution contracts with volume commitments written into them, the acquirer's reserve against chargebacks, the service desk sized for the week the weather turns (the same desk that earns its keep on the difficult bookings): those shrink slower than bookings do, and some of them do not shrink at all until the business stops.
Nor do they arrive evenly. Some come as sudden cash squeezes: a GDS clawing back incentives or sending a shortfall bill when segment commitments are missed (the standard agreements “allow the vendor to cut incentives”, as Travel Weekly's lawyer-columnist puts it), or a surcharge for an excessive look-to-book ratio, something the GDSs have stated contractually for ages and rarely enforced, and now enforce heavily because agents keep shopping, all the time, with little or no caching. Others are a slow bleed, a death by a thousand (paper) cuts. A genuinely small operation can linger cheaply. An agency with real volume cannot, because its costs and obligations retreat slower than its bookings.
As for what that 90% is a share of: no registry counts OTAs as a category; they count every agency that settles money with an airline. IATA's settlement system lists “59,000+ accredited travel agents” worldwide. ARC's 2025 US figures come from “9,978 U.S. retail and corporate travel agency locations and online travel agencies”. Eurostat counts 52,443 travel-agency enterprises in the EU in 2024, and that number is still rising.
This forecast is about a slice of those tens of thousands: today's standalone consumer OTAs, particularly independent leisure agencies and resellers, plus the far larger crowd of sellers that ride on somebody else's accreditation and never appear in those registries at all. By count, the population is dominated by its long tail: a domain, an ad budget, a markup, somebody else's ticketing and a search engine that used to send clicks. The harder half is the capable middle (accredited agencies with their own ticketing, their own service floors and real airline relationships), and that is where I expect to be argued with. I expect them to disappear too, only more slowly, and more often by being bought or transformed than simply shutting the doors. For the middle, survival is something a company has to choose, early and at a cost, rather than something it is owed for having been good at the old game.
Concentration has limits. Local supply, regulation, ownership rules and a traveller's trust can keep separate businesses alive, and regulators are watching the biggest consolidator: the Commission made Booking.com a gatekeeper under the Digital Markets Act in 2024. Easier integration helps a new specialist enter as readily as it helps a large group consolidate, and open access could cut the value of scale in some functions. For the field to hold its size, those sources of difference would have to replenish independent companies at least as fast as overlapping ones combine or close. They won't.
Timing is where the incumbents will push back. Booking's finance chief said in August that traffic from large language models, paid and unpaid, is “still significantly below 1% of our room nights”, and Expedia's chief executive calls agent traffic “small”. Both are true today and both measure the wrong thing: the share of bookings that arrive through an agent lags the share of decisions the agent already shapes. The near end of that range is aggressive; 2035 allows for the slower part, when companies are bought, contracts unwind and obligations outlast bookings. But valuations, reinvestment decisions and supplier negotiations can move years before agentic bookings dominate. The restructuring starts before the last consumer changes their habits.
The layer underneath can be bypassed too
Becoming a supplier buys a position in the next market. It does not buy permanence.
Etraveli is the serious counterexample to anyone claiming agents make agency execution worthless. Booking tried to buy it, and the European Commission blocked the deal in 2023 because it “would strengthen Booking's dominant position in the online travel agencies market” (the General Court upheld the prohibition in September). Booking.com then extended its flight partnership for eight years in 2025 anyway, when the offering covered 57 countries. A company with Booking's consumer reach wanted a specialist's flight execution badly enough to try to own it, and settled for renting it. Interfaces keep intermediaries when the intermediary is cheaper than the alternative, risk included. That is the whole test.
The airlines' motive has never been subtle. Lufthansa justified its 2015 surcharge on GDS bookings by saying the costs of GDSs “are several times higher than for other booking methods”, running to a three-digit million euro amount a year. They can also overreach: American Airlines' chief executive admitted of its own push to steer agencies onto direct channels, “we moved faster than we should have and we didn't execute well.” And they are already walking into the agents themselves. Virgin Atlantic calls itself “the first airline in the world to launch an app in ChatGPT”.
Booking's chief executive thinks the payment boundary is the moat. Asked whether the models would take over as merchant of record, Glenn Fogel said on the Q4 2025 call: “That's really hard,” and of the large language players doing it, “I don't know about that.” He is right that it is hard, and wrong that it protects the agency, because the models do not need to become merchants. They need somebody who already is, and that seat is for rent.
The route to the supplier is changing too. OpenAI's dots agent runs its own cloud browser and can connect to the user's laptop, and an agent operating where the customer already has a session is, to the site it visits, the customer.
That is not legal immunity. The Ninth Circuit's August opinion in Amazon v. Perplexity vacated a preliminary injunction under the federal and California computer-access statutes in a user-directed browser setting; the complaint it describes contained no contract claims, and the court expressly left Amazon's ability to regulate users through its own terms untouched. Terms and ticketing authority are where travel does most of its gatekeeping anyway. It settled neither every route by which a merchant could restrict an agent nor every future booking task.
Take that a few years out. A middleman that cannot tell a user from an agent ends up serving its pages to software that has been told to ignore every ad, every upsell, every bundle and every “only two seats left” banner, and to hunt for the best workable offer on one itinerary. Everything an OTA built to turn a visit into margin (the merchandising, the ancillary attach, the retargeting pixel, the newsletter sign-up) is aimed at a human who is no longer looking. What is left is the bare fare plus a markup, read by a machine that compares that markup with other sellers' and with the airline's own price, with no memory of the brand unless it was told to keep one. Nobody blocks the OTA. The agent simply stops finding a reason to book there.
The machine that searches everything
Travel fares are not deterministic in the way a consumer expects a price to be. Run the same search ten times, across ten sources, a minute apart, with the caches bypassed, and you can get different sets of results. Availability changes, fare construction differs, channels expose different inventory, and an offer that appeared seconds ago may no longer be bookable. This is why aggregators query so many suppliers in the first place. An agent that checks three sources because they worked last time will often be worse than one that checks twenty, and a worse agent will eventually lose the traveller. The winning agent will learn when a cached answer is good enough, when it needs to search wider, and which sources are most likely to have something the others missed. That does not preserve twenty OTAs. It makes the underlying search infrastructure more valuable while making the sellers it searches more interchangeable.
The same robot hits the cost side. Every one of those searches is a shopping request somebody pays to answer, and look-to-book (searches per completed booking) was punishing before any agent arrived: IATA found ratios for OTAs and metasearch “in the best case 1,000-to-1 but more commonly above 10,000-to-1”, against 100 to 300 on airlines' own sites. Agentic shopping, in the words of a former Amadeus executive quoted by PhocusWire, “could push the look-to-book ratio beyond 200,000:1”.
The limits are already written down. Qantas publishes a maximum acceptable ratio of 2,500:1 for NDC shopping, with throttling and suspension behind it; Duffel bills “$0.005 per excess search” past 1,500:1; Amadeus says overwhelmed carriers now “impose ‘look-to-book’ limits on travel agencies”; and Sabre sells caching so agencies can “protect against airline penalties”. The agent that strips the margin out of each visit multiplies the cost of each booking. Revenue per search falls while cost per search rises, from the same machine, and that is the middle getting squeezed from both sides at once.
The booking for that economy seat from YYZ to LGA may need no intermediary at all. The shopping still costs somebody money. Pretend a single scan costs $0.0000001; get that wrong by a few orders of magnitude and it is still tiny. A person who takes two or three flights a year costs next to nothing, even running a few scans before each one. Intermediaries all running the same searches, all the time, drive it up crazily. The full commercial cost of a live offer is not just the computational cost of a scan, of course. The point is that tiny unit prices become a real market when the machines make enough calls.
So maybe airlines release a cheap or free cache. Or a thin intermediary does. OAG probably could: it already holds “more than 4 trillion historical airfares”, gathered from airline websites, GDSs and OTAs and growing by 3.1 billion a day. A Borges-like Library of Babel for flight prices: nearly everything that ever flew, and no guarantee that anything on the shelf can still be booked. Historical data can narrow the search; only a live offer can settle it. The best caches sell themselves on “95% alignment to live airline offers”; that still leaves a meaningful problem of freshness and verification. Some GDSs could, because they already sell caches to the OTAs; Sabre launched its cache with Wego's chief executive, a pilot customer, “anticipating agentic flight shopping where look-to-book ratios increase asymptotically”. Or someone new does.
Or the airlines sell the live scan themselves. x402, the payment standard Coinbase launched in 2025, puts to work the web's “402 Payment Required” status code, which the web's reference documentation still lists as “reserved for future use”: a server answers an unpaid request with a 402, and the client pays and retries. Maybe airlines should make live scans exactly that kind of product, so that the same request a traveller sends today as a Google Flights search for two, Toronto to LaGuardia, May 9 to June 10, 2027, sent to the airline's own endpoint, returns a structured, bookable offer once a hypothetical fee of $0.0001 is paid, a thousand times the pretend computational cost of the scan. That could become its own business, yet again, or a new revenue line for most of the players now contemplating the future of agentic commerce in travel.
The function does not survive the agents unchanged; it gets repriced, and part of the margin that used to pay for a search screen moves to whoever sells the scan.
The next intermediary may not look like an agency
There is an irony in all this. The technology that makes most OTAs unnecessary may create a new generation of intermediaries, some considerably more powerful than the companies they replace. Duffel is an early example of what that can look like. A specialist that makes fragmented inventory reliably accessible to agents can earn a valuable position without owning the traveller or maintaining a consumer storefront.
But the same architecture gives airlines and hotels a way around those new intermediaries too. Suppliers have spent decades trying to reclaim distribution from companies charging them for access to their own customers. Agents that can reason about fares, assemble itineraries and call suppliers directly offer another chance. Some of the old spread will concentrate in new hands. Some will return to suppliers. Some will disappear into lower prices or lower distribution costs.
And the intelligence need not live in the same company as the booking operation. A general-purpose personal assistant can understand the traveller, while a specialist model trained on fare construction, routing, supplier behaviour and distribution rules works out which sources to call and how to assemble a workable journey. Better harnesses and callable interfaces, including MCP-style tools, can connect that intelligence to caches, GDSs, airline APIs and servicing providers. The model doesn't magically acquire live availability, ticketing authority or the right to issue a refund. It gets better at deciding which systems to ask, in which order, and which claims to verify before the traveller pays.
This is what composability means in practice. The expertise that used to be bundled with a consumer acquisition machine can become a service bought by an agent, a supplier or another specialist. The next intermediary may have no homepage worth visiting, no newsletter and no consumer brand. It might be enormous. It might be a handful of engineers with a narrow piece of inventory and a very good interface. Or the airline may decide to do the same job itself.
The interesting question is not whether travel will still have middlemen. It will. It is which functions will still require one, how much they can charge, and how long they can prevent the next agent from reaching around them.
The middle built real things
If this essay has an elegy, it is for the independent innovators, who built capabilities the airlines and the big agencies did not want to build and then persuaded travellers to trust the result.
Virtual interlining is the case I know from the inside: stitching flights together across airlines that have no interline relationship with each other, and selling the result as one trip. We did it first, at FlightNetwork, where a lot of the full-service and low-cost combinations were ours before anyone else sold them. Dohop, which began as a flight search engine sending travellers on to the airlines to book, came after, and made a business of selling the capability to airlines themselves: its chief executive calls working directly with airlines “really the foundation of our business”, easyJet's connections service in 2017 was “enabled by technology partner Dohop”, and Scoot launched a virtual interline platform with it in 2025.
Kiwi.com got the consumer product really well, and describes itself as the start-up that “brought the then unknown concept of Virtual Interlining to the world”; its guarantee wraps assistance and remedies around the journeys that need them. Only FlightNetwork spun it out as its own B2B company: TripStack, founded in Toronto in 2016 and part of Etraveli Group since 2019, which OAG counts as “one of the first technology companies to offer virtual interlining fares”. Finding the combination and standing behind the failed connection are different contributions. Agents will commoditise the first long before the second, and the airlines buying the first straight from Dohop have already started. A specialist model will be very good at the first: finding the combination nobody else spotted. Confirming that the parts are bookable together at the quoted price, and standing behind them when a connection fails, is the second, and that is the part that stays expensive.
Etraveli's contribution is broad execution. eDreams ODIGEO built a membership relationship with consumers and reported 8.1 million Prime members in its latest quarterly release. lastminute.com has put its flight search in front of agents through an agent-facing server that hands the final booking back to its own site, the same instinct as Expedia's. Different answers from companies that are plainly not sitting still.
The engineering was real and so was the customer relationship. An agency can lose the economic independence of both without having built anything badly. When comparison, composition and execution all arrive through one interface, several capable firms end up supplying overlapping value, and the market pays the combined operation more than it pays each separate company. Competence was never the question.
Scale buys options
Booking, Expedia and Trip.com have more ways to answer the problem: familiarity that survives delegation, membership that carries a preferred supplier into the conversation, a partner business that keeps selling when direct demand shifts. None of it is a reserved seat. BCG's hospitality scenarios include an LLM-and-OTA partnership model in which OTA and GDS profit pools stay largely stable; it is a credible counterforecast about the pools and says nothing about how many firms share them, and stable pools split among fewer firms is part of my point.
A few escapes, for a few companies
The routes through are visible. Each protects a different contribution, and each has something an improving agent or a stronger counterparty can take away next.
Sell membership instead of trips. An agency with recurring consumer commitment has a relationship to carry into the agent. Membership has to keep producing value the agent can see when it runs the arithmetic, which it will, at every renewal; an agent that does the sums is an uncomfortable new member of the household. Retention has to earn its keep.
Sell to whoever already owns the customer. Banks, airlines, consumer platforms and agents can buy travel capability rather than build it. The supplier has to price and operate for that buyer. A large contract can replace a great many paid clicks; it also concentrates demand in a customer who can negotiate, switch or insource. The capability has to stay useful after the client has learned the business.
Own the mess after the booking. Disruption, reissues, refunds and unusual itineraries need accountable execution, and a specialist with the right access and service economics can live on them. Agents will get better at this work too, and carriers may expose better direct tools. The defence is resolving difficult journeys reliably, not assuming nobody else's software will learn to handle a cancellation.
Carry inventory an agent cannot assemble. Contracts, relationships and routing knowledge can produce offers a generic comparison cannot reproduce. I will describe the shape of that asset here and not its mechanics. The scarcity has to survive the counterparties' own distribution choices, because wider access or a direct offer from the airline erodes a private advantage without making the original work any less clever.
Become the agent's supplier. Structured, callable execution gets an agency into the new channel. It still needs demand, retained contribution and a reason to receive the next call. An API makes the business accessible, which is a long way from necessary. The OTA endgame can be profitable supply beneath the agent, but that is an outcome to earn, not a job title to adopt.
Be the consolidator, and know what that means. Buying contracts, capabilities and service operations can make a better supplier and remove duplicated cost. Buying several declining traffic streams makes a larger bill. The acquirer needs a clear account of what survives the integration, what its counterparties will permit and which costs actually leave. Scale should do work.
There are at least two more routes that I am keeping out of a public essay. One depends on a kind of inventory whose counterparties would rather not read its mechanics in print. The other depends on timing, and publishing it would spend the timing.
Every one of the six is a turnaround. Each changes the revenue model, the cost structure and usually the customer, while the old business is still paying the bills and the board is still reading last year's dashboard. Shipping a connector is easier than replacing the economics of a consumer company.
Most companies attempting the transition will not complete it. The exceptions will need leaders who understand the travel industry's commercial constraints as well as the technology: which revenue can fund the transition, which costs have to leave early, and which relationships cannot be rebuilt once they break. Experience taking a company through comparable change will matter, and the owners who bring that capability in early will have better odds. The scarcity is operational before it is technological.
Receipts
I have been circling this argument for two years, mostly one quarter at a time, and the post-search internet it assumes was sketched here before any of these launches happened. The component pieces, not that I am obsessed or anything: 1 2 3 4 5 6 7. None of them is required reading for what is above.
The first-choice destination goes first. Convergence then removes the reasons for separate companies to stay separate, and consolidation takes the useful parts into fewer hands. A minority stays independent by earning a different job. The spread outlives most of the companies that collected it, and the agents keep testing which layer deserves to collect it next.
Questions for leaders
If direct traffic halved over three years, which revenue lines would still be profitable after the costs you could actually remove?
What would an agent lose by replacing you with another supplier, or by going direct?
Which of your customers could bring the work inside, and what keeps buying from you the better decision?
If you bought a rival tomorrow, which capabilities would become more valuable and which duplicated costs would really leave?
Who on the leadership team has run the kind of turnaround your answers require?
—TJ